We assess roof damage, document the loss, and represent policyholders in insurance claim disputes in Palmer Ranch, Florida. In the first visit we tell you what the insurer is likely to cover and what documentation will matter in a dispute.
What a roof damage assessment is and why it matters
A roof damage assessment is a focused review of visible and likely hidden loss to roofing materials and related structures after an event. For insurance claim disputes the assessment matters because insurers base most settlements on scope, cause, and cost. With more than 30 years of insurance adjusting experience, we evaluate how an insurer will view cause, wear and tear, and required repairs.
In Palmer Ranch, hurricane wind, wind driven rain, and storm debris are common causes of roof damage. That local context changes how we document damage and present the claim to an insurer.
Common types of roof damage we see in Palmer Ranch
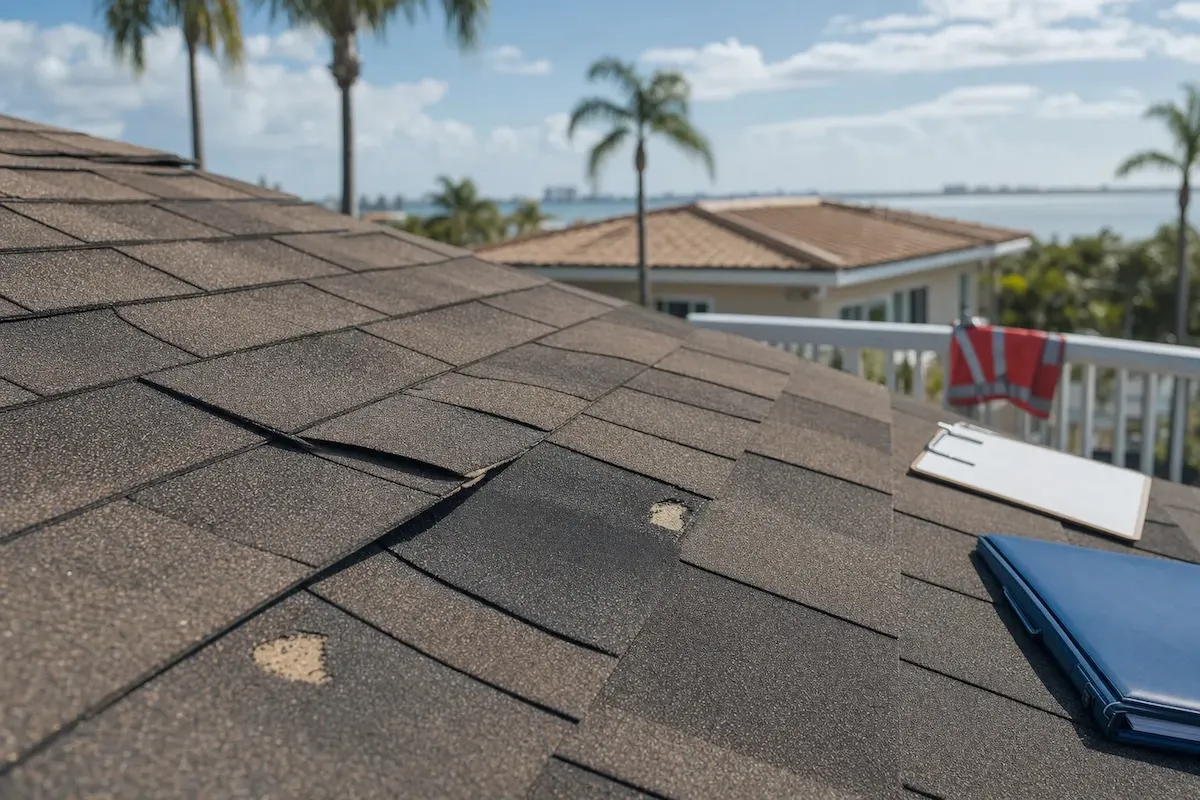
- Wind uplift and missing shingles on asphalt composition roofs.
- Cracked or displaced tiles on concrete or clay roofs.
- Water intrusion from compromised flashing or ridge vents.
- Granule loss and embedded debris that accelerates wear.
- Structural damage to roof decks after long term leaks or storm impact.
How we approach a roof damage assessment for an insurance dispute
We do not instruct homeowners to climb on roofs. Our approach focuses on safe inspection, careful documentation, and claim strategy.
- Case intake and policy review. We start by reviewing your insurance policy, coverages, exclusions, and any applicable endorsements. That frames what can be claimed.
- On site inspection and documentation. We inspect the roof from safe vantage points, photograph damage, and note construction type, age, and prior repairs.
- Estimate and scope preparation. We assemble contractor estimates or third party repair scopes that show repair versus replacement costs and line item pricing.
- Insurer interaction and leverage. We compare the insurer adjuster report to our documentation, identify gaps, and use our adjusting experience to explain why certain items are covered.
- Dispute, appraisal, or litigation as needed. If the insurer denies or underpays, we discuss options such as appraisal, demand packages, and formal dispute procedures.
Watch out: Walking on a damaged roof can cause injury and can worsen damage. Let trained inspectors or contractors access the roof safely. If you see active leaks, protect interiors with temporary measures and document the condition.
What good documentation looks like
Well organized documentation often determines the outcome of a roof claim. We help clients assemble a straightforward record that an insurer can verify.
Documentation checklist
- Clear timestamped photos of damaged areas from multiple angles.
- Photos of undamaged areas for comparison.
- Contractor estimates, repair scopes, or invoice history.
- Roof age and prior maintenance records, if available.
- Weather reports or local storm data that correspond to the damage date.
Pro tip: Take exterior photos before any temporary tarping when possible. If temporary repairs are needed, keep receipts and photograph both the tarped condition and the underlying damage once accessible.
How our adjusting background changes a claim
Because Tom worked as an insurance claim adjuster for decades, we know how insurers evaluate roof loss. That knowledge helps us identify undervalued line items, missing cause analysis, and incorrect depreciation.
We do not replace a licensed roofing contractor. Instead we coordinate estimates, explain repair terminology to the insurer, and argue for correct scope and pricing when the insurer undervalues a repair.
When appraisal or arbitration becomes necessary
Some policies include appraisal or alternative dispute clauses. Appraisal can resolve disagreements about the amount of loss while appraisal cannot change coverage positions. When coverage is denied we consider other dispute options.
If the process looks like it will involve formal evidence or expert testimony, we assemble the necessary reports and show the insurer where their evaluation diverges from industry practice and local building standards.
Information homeowners should collect before we start
Gathering material up front speeds resolution. The more complete your file, the better we can make your case.
- Policy declarations and any recent endorsements.
- Photos of the roof and interior water damage.
- Contractor scopes, bids, or repair invoices.
- A chronology of communications with the insurer and adjuster notes.
- Any prior roofing permits or work orders, if available.
Related topics and next steps
Documentation shapes roof damage disputes, which is why we recommend a careful review before filing a formal disagreement. See our guidance on claim documentation to learn what evidence is most persuasive for an insurer.
For a summary of how insurance claim disputes proceed in our practice, see our Insurance Claim Disputes service overview. If you live in the wider Sarasota area, our Sarasota, Florida location page explains the communities we serve and local considerations.
Key takeaway
A timely, well documented roof assessment changes the outcome of many insurance disputes in Palmer Ranch. Our combination of adjusting experience and legal advocacy helps policyholders present complete claims and press for fair recoveries when insurers fall short.
Frequently asked questions
Can I file a roof claim for storm damage after a delay?
It depends on your policy and the facts. Insurance policies include notice and time limits and legal statute of limitations may apply. We review your policy and the timeline to determine whether a late claim can still proceed.
Will the insurer pay for a full roof replacement?
Coverage depends on cause, policy language, and the extent of damage. Carriers may pay replacement cost for sudden storm damage but may limit payment for wear and tear. We evaluate cause, scope, and depreciation to present the strongest case for replacement when it is necessary.
What is the appraisal process and should I use it?
Appraisal is a contractual process many policies provide to settle disputes over the amount of loss. Appraisal does not resolve coverage disputes. We assess whether appraisal is likely to be effective or whether other dispute avenues are better given the coverage issues involved.
How does diminished value affect a roof claim?
Diminished value usually applies to vehicles. For property claims, diminished value concepts can affect market damage arguments for structures in some contexts. We handle diminished value claims for autos and discuss property value impacts when they are relevant to your dispute.
Is it safe to document damage myself?
Yes, you can take photos and keep invoices. Avoid climbing on a damaged roof. Use ground level photos and clear interior shots of leaks. Keep records of communications with the insurer and save contractor estimates and receipts.
Where to learn more and how to check our reputation
Read reviews and get directions on our Google Business Profile, and use that information to see how we handle local roof and storm claims in Palmer Ranch.